LIV Golf Thrown a Lifeline as BC Partners Commits Funding, Player Deadline Pushed to Oct 25
LIV Golf has secured an initial financial commitment from BC Partners as part of a targeted $300 million investment to pull the league out of bankruptcy, and the deadline for players to commit to "LIV 2.0" has been pushed back nearly two weeks to October 25.
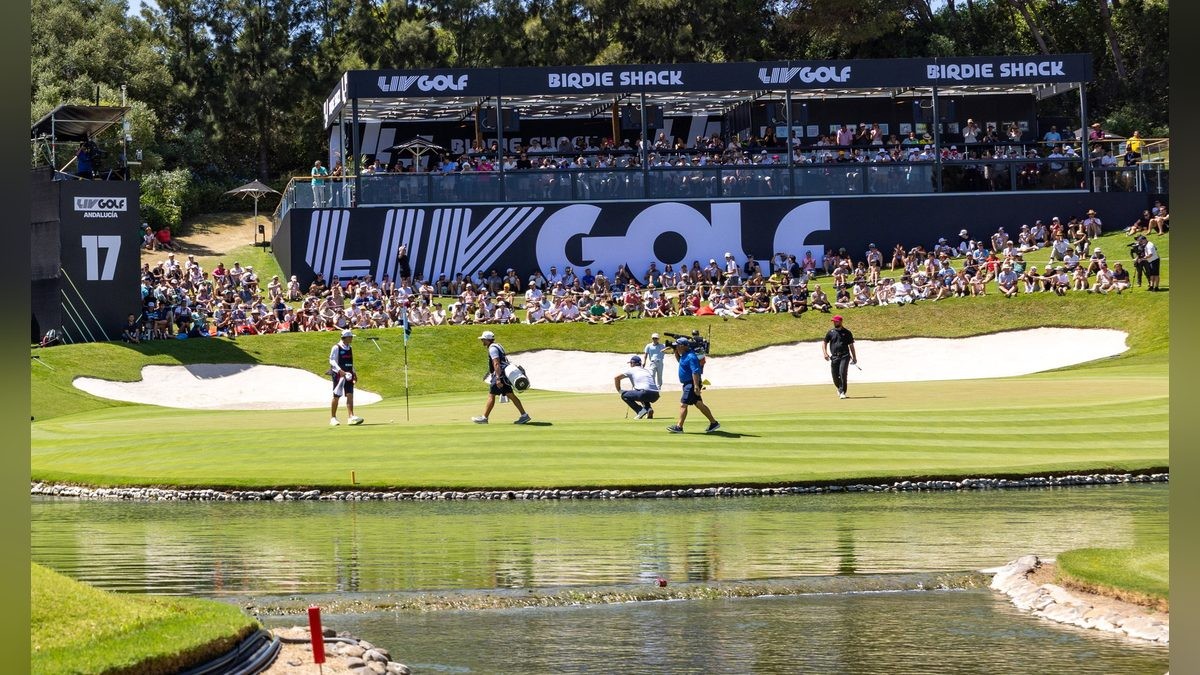
LIV Golf's fight for survival took a significant step forward on Monday when BC Partners announced it had made an initial financial commitment to the embattled league as part of a targeted $300 million investment. Court documents filed on Oct. 5 show the private-equity firm agreed to an "initial participation" of $4 million, though the funding still needs approval from the bankruptcy court and Saudi Arabia's Public Investment Fund. As part of an amended restructuring agreement, BC Partners also pushed the deadline for players to commit to the new player-owned "LIV 2.0" model from Oct. 13 to Oct. 25, giving stars more time to decide whether to stay or walk away. Under the proposed structure, players would own 52.5% of the reorganized parent company, with 45% going to new investors and 2.5% to management. The PIF must approve the deal by Oct. 30, with a target effective date of Jan. 6, 2027. The update came with fresh signs of player unrest: Sergio Garcia has been granted permission to terminate his LIV contract if he chooses, while Joaquin Niemann admitted this week he is weighing whether to return to the PGA Tour. The league, which filed for Chapter 11 protection on Sept. 8 after the PIF pulled its backing, plans a slimmed-down 2027 season of 10 events. Its next court hearing is Wednesday.